Britain's Wagering Evolution: Uncovering the Latest Shifts in Gambling Preferences and Technologies
Written by Yara Krause · Sep 26, 2026
UK Gambling Commission Releases Annual Figures on Industry Performance for 2025-2026
The UK Gambling Commission has published its Industry Statistics covering the financial year from April 2025 to March 2026, and these figures detail a 4.4 percent rise in total gross gambling yield that reached £17.5 billion, while the amount excluding lotteries climbed 4.7 percent to £13.2 billion.
Breakdown of Overall Growth Trends
Observers note that the remote casino sector accounted for much of the expansion, with combined GGY from remote casino, betting, and bingo operations hitting £8.3 billion after a 6.9 percent increase, and data from the report links this performance directly to shifts in player participation across digital platforms during the period.
Within that category, online casino GGY alone advanced 14.8 percent to £5.7 billion, which researchers attribute to sustained demand in virtual gaming environments, while traditional land-based segments showed more modest movement or outright contraction in physical locations.
Changes in Retail Betting Infrastructure
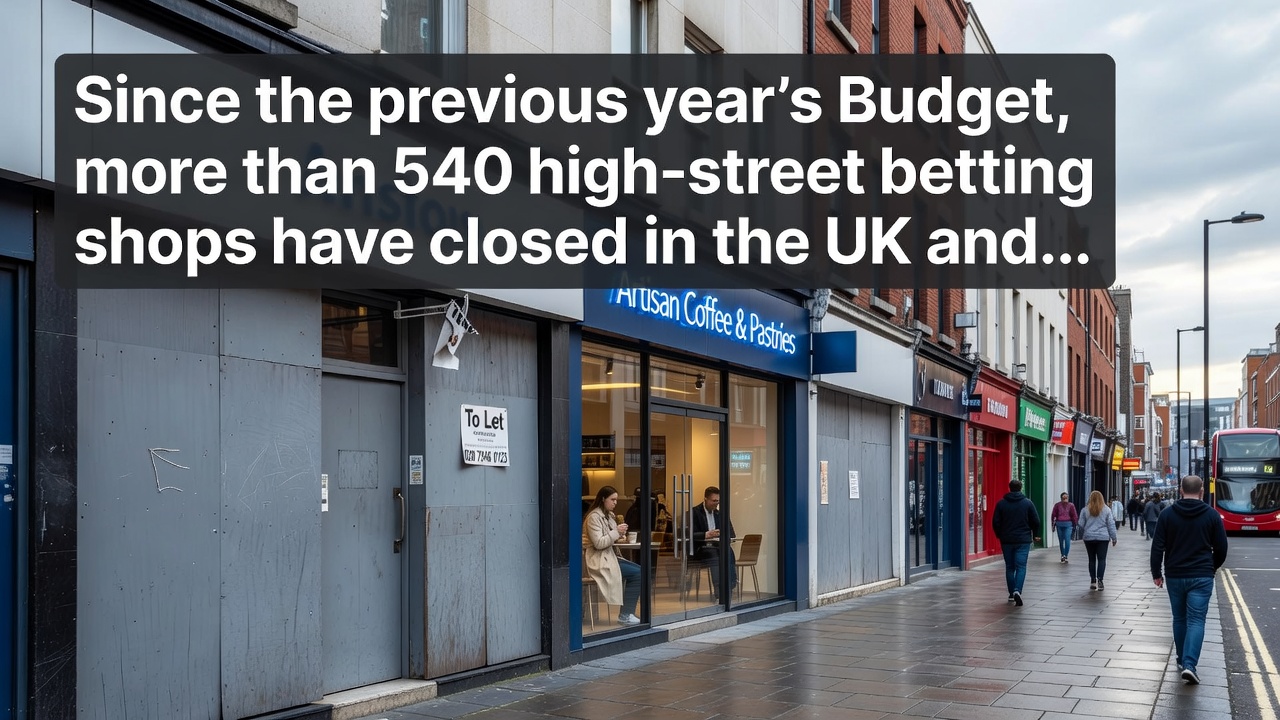
The number of betting shops declined 3.6 percent to 5,617 outlets by the end of the financial year, and this reduction reflects ongoing consolidation patterns that have characterized the high-street segment for several reporting cycles, according to the same set of official statistics.
Those who track industry infrastructure point out that operators have continued to adjust their physical footprints in response to evolving consumer preferences, yet the overall GGY contribution from remaining retail sites maintained stability even as counts fell.
Sector-Specific Performance Details
Remote betting activities formed a core part of the £8.3 billion remote total, and the report separates these from bingo and casino lines to highlight how digital channels absorbed much of the year-on-year uplift, whereas lottery-inclusive totals reached the headline £17.5 billion mark through separate growth channels.
Experts examining the full dataset observe that the 14.8 percent jump in online casino GGY outpaced the broader remote average, which suggests differential growth rates across product types even within the same delivery mode, and the commission's annual release presents these numbers without adjustment for inflation or other external factors.
Land-based betting shops, by contrast, operated against a backdrop of fewer locations, yet their aggregate yield remained integrated into the non-remote calculations that feed into the £13.2 billion excluding-lotteries figure, and analysts continue to monitor how this balance evolves in subsequent quarters.
Context Within Recent Publication Timing
The statistics appeared in September 2026, several months after the March 2026 close of the financial year, which allows the commission to compile verified operator returns before release, and readers can access the full breakdown through the linked official statistics page for granular tables on each sub-sector.
People who follow regulatory reporting cycles note that this timing aligns with prior annual releases, providing a consistent reference point for comparing year-over-year movements across remote and non-remote activities alike.
Conclusion
The 2025-2026 Industry Statistics therefore document measured expansion in total gross gambling yield alongside contraction in physical retail outlets, with remote casino operations driving the largest percentage gains, and these facts stand as recorded in the Gambling Commission's official publication for the period ending March 2026.